This book presents a cogent description of the main methodologies used in derivatives pricing. Starting with a summary of the elements of Stochastic Calculus, Quantitative Methods in Derivatives Pricing develops the fundamental tools of financial engineering, such as scenario generation, simulation for European instruments, simulation for American instruments, and finite differences in an intuitive and practical manner, with an abundance of practical examples and case studies.
Intended primarily as an introductory graduate textbook in computational finance, this book will also serve as a reference for practitioners seeking basic information on alternative pricing methodologies.
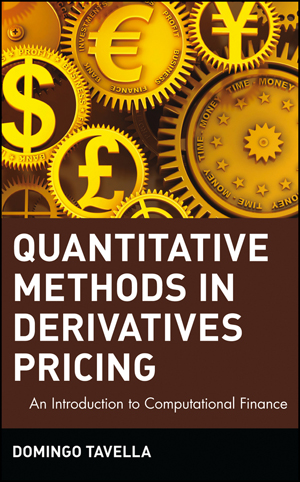

Author(s): Tavella, Domingo
Publisher: John Wiley & Sons
Collection: Wiley Finance
Pub. Date: 2002
pages: 305
Language: lang_en
ISBN: 978-0-471-39447-1
eISBN: 978-0-471-27479-7
This book presents a cogent description of the main methodologies used in derivatives pricing. Starting with a summary of the elements of Stochastic Calculus, Quantitative Methods in Derivatives Pricing develops the fundamental tools of financial engineering, such as scenario generation, simulation for European instruments, simulation for American instruments, and finite differences in an intuitive and practical manner, with an abundance of practical examples and case studies.
Intended primarily as an introductory graduate textbook in computational finance, this book will also serve as a reference for practitioners seeking basic information on alternative pricing methodologies.